Fort Worth Car Accident Attorney Insights
By Jesse Lotspeich · Car Wreck
Fort Worth Car Accident Attorney Insights: How to Secure Fair Compensation and Legal Support
If you or a loved one have been injured in a Fort Worth car accident, this guide explains how Texas law, immediate actions, and skilled legal advocacy combine to protect your rights and maximize recovery. You will learn the key Texas rules that govern fault and filing deadlines, step-by-step actions to preserve evidence and health, the kinds of compensation available, and how attorneys can investigate, negotiate, and litigate on your behalf. Howard Lotspeich Alexander & Williams, PLLC provides free consultations and handles injury cases on a contingency-fee basis, meaning no upfront attorney’s fees for qualified clients, which can help people focus on recovery rather than legal bills. The article maps practical next steps, legal concepts like comparative fault and the statute of limitations, scenario-specific strategies for truck or motorcycle collisions, common injury impacts, and local resources to contact. Read on for clear, actionable advice tailored to Fort Worth and Tarrant County accident victims and families who need timely legal and medical guidance.
What Are the Key Texas Laws Affecting Fort Worth Car Accident Claims?
Texas law shapes how Fort Worth car crash claims are evaluated, assigning responsibility, limiting filing time, and defining negligence elements that plaintiffs must prove. Understanding the modified comparative fault rule and the two-year statute of limitations is crucial because these legal rules directly affect whether and how much you can recover after a wreck. This section summarizes core statutes and practical effects for victims, then breaks down comparative fault, filing deadlines, and the negligence elements you must establish to succeed. Knowing these legal guardrails early helps preserve claims and prioritize evidence collection that influences fault and damages.
Texas statutes and rules that commonly control Fort Worth crash claims appear below to clarify what each law governs and how it impacts injured parties.
This table shows the key statutes and how they influence practical decisions such as filing suit, preserving evidence to disprove or limit assigned fault, and determining whether a wrongful death action is an available remedy. Understanding each rule early drives the next steps an injured person should take.
How Does Texas Comparative Fault Law Impact Your Car Accident Case?
Texas follows a modified comparative fault rule with a 51% bar, meaning a plaintiff who is 51% or more responsible cannot recover damages. Courts and juries assign percentages of fault to each party based on evidence such as police reports, witness statements, video, and expert testimony, and a plaintiff's recoverable damages are reduced by their assigned percentage if they remain below the 51% threshold. Demonstrating lower fault often hinges on timely evidence collection and preserving records that counter insurance narratives. Because percentage allocation is fact-specific, early investigation and targeted evidence gathering help limit a plaintiff’s comparative fault and preserve settlement or trial value.
This rule makes documenting the scene and collecting corroborating evidence essential; the next subsection covers time limits to file suit and exceptions that can affect how long you have to act.
What Is the Statute of Limitations for Filing Car Accident Lawsuits in Texas?
The general statute of limitations for personal injury claims in Texas is two years from the date of the injury, and wrongful death claims typically must be filed within a similar two-year period from the date of death. Exceptions or tolling can apply in limited circumstances — for example, when a claimant is a minor or the injury is discovered later, but those exceptions are fact-dependent and require prompt legal evaluation. Missing the statutory deadline usually prevents filing a lawsuit, which is why it is critical to consult counsel early to evaluate any potential exceptions and ensure timely preservation of claims. Acting quickly also helps secure evidence that supports liability and damages before it is lost or degraded.
Timeliness and fault allocation interrelate: preserving evidence early supports both proof of liability and protection against comparative fault reductions.
How Does Texas Law Define Liability in Fort Worth Auto Accidents?
Texas negligence law requires a plaintiff to prove four elements: duty, breach, causation, and damages, and these elements apply to Fort Worth car wreck cases where drivers owe a duty to exercise reasonable care. Establishing breach typically relies on evidence of negligent acts — speeding, failing to yield, distracted driving — while causation links the breach to the plaintiff’s injuries through medical records and expert opinions. Damages include past and future medical costs, lost earnings, and non-economic losses like pain and suffering, all of which must be supported by documentation. Effective presentation of these elements combines witness testimony, police reports, medical records, and, where applicable, expert analysis to connect conduct to harm and quantify losses.
Proving liability in the local Fort Worth context often requires swift investigative steps to collect scene evidence and preserve statements that corroborate the negligence elements described above.
What Steps Should You Take Immediately After a Car Accident in Fort Worth?
After a crash in Fort Worth, prioritized actions protect health and preserve the legal value of a claim: secure safety, obtain medical care, document the scene, and report the incident. Taking these steps not only safeguards victims but also creates an evidentiary foundation that supports liability and damages claims, reducing the risk that insurers will dispute causation or underpay compensation. This section gives a practical, prioritized checklist suitable for immediate use at the scene and in the hours after a collision.
Follow this numbered checklist to protect yourself and your claim immediately after a Fort Worth car wreck.
- Call 911 and seek emergency care if anyone is injured, and follow first-responder instructions at the scene.
- Move out of hazardous traffic when safe, turn on hazard lights, and avoid admitting fault while speaking with others.
- Photograph vehicle positions, visible damage, road conditions, skid marks, traffic signs, and any injuries, using time-stamped images where possible.
- Collect names, phone numbers, and insurance information from witnesses and other drivers, and request a responding officer’s name and report number.
- Obtain prompt medical evaluation, even for seemingly minor symptoms, and keep detailed records of all treatment and diagnoses.
Completing these steps increases the quality of evidence available for insurance negotiations or litigation, and the next section explains best practices for documenting the scene in more detail.
How to Safely Document the Accident Scene and Collect Evidence
Documenting the scene begins with wide-angle photos to record vehicle positioning and then closer shots of damage, license plates, traffic controls, and contributing roadway conditions. Video of the surrounding area, timestamps, and audio notes describing what happened add context that helps reconstruct the collision later, and obtaining witness contact information preserves critical third-party observations. Preserve physical evidence such as torn parts or personal items in a secure place and avoid altering the scene beyond safety needs; if law enforcement directs handling, follow the officer’s instructions. Consistent documentation strengthens the ability to prove fault and rebuts common insurance defenses.
Effective scene documentation flows naturally into prompt medical attention, which is essential for linking injuries to the crash in a claim.
Motor Vehicle Accident Data Preservation Guide
ABSTRACT: Simple techniques are presented for gathering and preserving motor vehicle accident data. The data are selected to meet the minimum information requirements of police, judicial, industrial, governmental, safety, and insurance interests. It is recognized that the information needs for accident investigators are as broad as the range of accident types and severities. The paper is structured so that the investigator may use it as a guide to selectively choose tasks according to their importance in documenting and reconstructing the accident and the availability of time and technical resources. A list of priorities for the data collection process which maximizes the efficiency and resources of the investigator is outlined and a cue card which may be used as an on-scene aid is provided.
Minimum Guidelines for Efficiently Acquiring or Preserving Basic Information in a Motor Vehicle Accident, 1988
When and How to Seek Medical Treatment After a Car Wreck
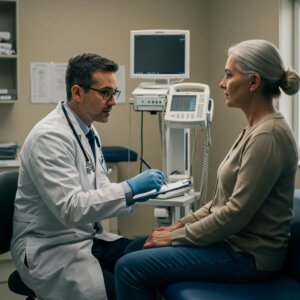
Seeking medical treatment promptly is both a health priority and a legal necessity: contemporaneous medical records create a causal link between the crash and injuries that insurers often require. Some injuries, such as whiplash or mild traumatic brain injury, can present delayed symptoms, so a cautious approach includes an initial clinical evaluation and follow-up care as recommended. Maintain copies of emergency reports, imaging studies, therapy records, and medication prescriptions to document the progression and cost of care. Clear medical documentation supports claims for both economic and non-economic damages and reduces insurer arguments that treatment gaps undermine causation.
Documenting medical treatment and communicating symptoms consistently to providers further supports accurate diagnosis and legal claims, which leads into guidance on insurer reporting.
What to Know About Reporting Your Accident to Insurance Companies
Notify your own insurer promptly to open a claim, but be cautious about recorded statements or accepting early settlement offers from other parties’ insurers without consulting counsel. Provide factual information — time, location, and basic circumstances — but avoid speculative statements about fault or downplaying symptoms. Keep a written log of all communications with insurers, including dates, names, and subject matter, and do not sign releases or accept final offers until you understand the total value of your damages. Consulting an attorney before providing detailed recorded statements can protect claim value and ensure your legal rights are preserved.
Careful insurer interactions help maintain negotiating leverage and set the stage for whether a negotiated settlement or litigation will be necessary later.
How Do Fort Worth Car Accident Lawyers Help You Maximize Compensation?
Car accident attorneys in Fort Worth help maximize compensation through thorough investigation, accurate valuation of damages, skilled negotiation with insurers, and litigation when necessary to secure fair results. Attorneys assemble evidence, work with medical and life-care experts, and leverage investigative teams to preserve scene data, obtain cell-phone records or vehicle data, and establish liability against negligent parties. Legal counsel also quantifies present and future losses — including medical expenses, lost earning capacity, and pain and suffering — and negotiates settlements designed to cover ongoing care and economic needs. When disputes persist, experienced trial attorneys prepare and present cases to juries in Fort Worth and Tarrant County courts to pursue full recovery.
This comparison clarifies how different damages are proven and why detailed documentation and expert support are critical to maximizing recovery. The next subsection explains contingency-fee arrangements that align client and attorney incentives.
What Types of Compensation Can You Claim After a Car Accident?
Victims can pursue economic damages (medical costs, lost income, property damage) and non-economic damages (pain and suffering, loss of enjoyment), and in rare cases punitive damages may be available when conduct is especially egregious. Each category requires supporting evidence: bills and medical records for economic losses, and consistent medical documentation plus testimony for non-economic harms. Future losses, like long-term care or diminished earning capacity, often need life-care plans and vocational or medical expert opinions to quantify. Assembling this evidence early helps attorneys present a comprehensive valuation during negotiation or at trial.
Proper documentation of economic items and expert-backed projections helps translate physical and emotional harm into recoverable compensation.
How Does a Contingency Fee Agreement Work With Fort Worth Attorneys?
A contingency fee agreement means the lawyer’s payment is a percentage of the recovery, so clients typically pay no upfront attorney fees and fees are due only if the case yields a recovery; this aligns incentives between client and counsel. Clients should confirm in writing the percentage, how costs and expenses will be handled (advanced or deducted), and what happens if the case is lost. Understanding how fees and litigation costs are managed helps clients make informed decisions without facing out-of-pocket legal bills while pursuing recovery. Always review the written contingency agreement carefully and ask questions about the calculation of net recovery.
Knowing fee structure allows injured persons to seek representation without immediate financial barriers, which supports access to thorough investigation and advocacy.
Why Choose Howard Lotspeich Alexander & Williams for Your Car Accident Case?
Howard Lotspeich Alexander & Williams, PLLC focuses on helping Fort Worth accident victims and families obtain legal support, recover damages, and navigate insurance claims after car accidents and wrongful death. The firm maintains offices in Fort Worth and Keller, uses investigative teams to gather evidence, and offers free consultations while handling cases on a contingency-fee basis so clients have no upfront attorney fees when qualifying. Named attorneys associated with the practice include Jason Howard, Luke Williams, Jesse Lotspeich, and Ashley Gilmore, and the firm reports a proven track record of recovering significant compensation and recognition among peers and local publications. bhwlawfirm.com If you need a confidential evaluation of liability and damages, scheduling a free consultation with experienced local counsel can clarify options and preserve critical deadlines.
This firm-specific information supplements the broader guidance above and connects injured Fort Worth residents with local resources for case evaluation and next steps.
What Are Common Car Accident Scenarios and Injuries in Fort Worth?
Fort Worth crash patterns include distracted driving, impaired driving, truck collisions, motorcycle accidents, and hit-and-run incidents, each presenting distinct evidentiary and liability issues. Local road types, commercial corridors, and traffic volume influence how these scenarios occur and how claims must be investigated, with truck and motorcycle cases often requiring specialized evidentiary steps. Identifying the crash type guides what records to obtain — for example, trucking logs or helmet-use details — and which experts to consult. This section outlines legal strategies for common scenarios so victims understand the differing burdens of proof and investigative needs.
- Distracted driving: preserve phone records and video evidence to show inattention.
- Drunk or impaired driving: obtain BAC and arrest reports to support civil claims.
- Truck accidents: gather logbooks, maintenance records, and carrier information.
- Motorcycle crashes: document helmet use and rebut biases that may affect liability.
Understanding the scenario informs the next steps for evidence gathering and selecting appropriate legal and medical experts to support claims.
How Are Distracted Driving Accidents Handled Legally in Fort Worth?
Distracted driving claims rely on evidence showing the driver failed to exercise reasonable care due to inattention, often proved through phone records, eyewitness testimony, dash-cam or surveillance video, and admission statements. Investigators prioritize preserving any electronic data and obtaining witness statements quickly, because these records can be altered or lost over time. Legal strategies focus on connecting the distraction to the breach of duty and demonstrating causation for the resulting injuries and damages. Given the prevalence of cell-phone use, effective proof of distraction can substantially increase settlement value and lessen arguments that fault lies elsewhere.
Collecting digital and physical evidence early is essential; the following subsection describes how intoxication evidence affects civil claims.
What Legal Options Exist for Drunk Driving and Impaired Driving Accidents?
Drunk driving crashes may result in both criminal prosecution and civil claims, and criminal records or BAC results can strengthen civil liability and, in some cases, support punitive damages for particularly reckless conduct. Civil attorneys use arrest reports, chemical test results, and field observations to establish intoxication and negligence, while coordinating with criminal case records when available. The existence of criminal charges is not required for civil recovery, but it often simplifies proof of fault and supports arguments for higher damages. Victims should preserve all official reports and seek counsel to evaluate whether enhanced civil remedies are available based on the facts.
When intoxication evidence is strong, attorneys can pursue fuller compensation and consider punitive damages where the law permits.
How Are Truck and Motorcycle Accident Claims Different in Fort Worth?
Truck claims are complex because liability can extend beyond the driver to the carrier, vehicle owner, maintenance providers, or manufacturers, requiring additional records such as driver logs, inspection reports, and black-box data. Investigations into truck crashes often involve subpoena power and specialized accident reconstruction experts to determine whether federal or state safety rules were violated. Motorcycle claims face different defenses, including bias against riders and arguments about helmet use or lane-splitting, so attorneys must proactively counter stereotypes with strong factual and medical evidence. Both types of cases typically benefit from firms with investigative capabilities and experience handling commercial transport and motorcycle nuances.
These distinctions highlight why selecting counsel with relevant investigative resources and subject-matter experience matters for complex collisions.
What Should You Know About Hit and Run Accident Claims?
In hit-and-run incidents, the immediate priority is reporting the crash to the Fort Worth police and documenting all available witness information and scene evidence to aid in identifying the fleeing driver. If the at-fault motorist is not found, victims may pursue uninsured/underinsured motorist (UM/UIM) claims under their own policy, provided such coverage exists and is applicable. Investigative techniques include canvassing nearby surveillance footage, interviewing witnesses, and working with law enforcement to locate the responsible party. Prompt reporting and evidence preservation improve the chances of identifying the driver or supporting UM/UIM recovery when the motorist cannot be located.
Timely police reports and witness contact information are often decisive in progressing hit-and-run claims or UM/UIM coverage actions.
What Are the Most Common Injuries From Fort Worth Car Accidents and Their Legal Impact?
Car accidents in Fort Worth commonly cause soft-tissue injuries, traumatic brain injuries (TBI), spinal cord injuries, and fatalities, and the severity of injury heavily influences case strategy and damages valuation. Catastrophic injuries require life-care planning, long-term medical projections, and specialized expert testimony to quantify future costs, while less visible injuries need consistent medical documentation to overcome insurer skepticism. This section maps common injuries to typical legal implications and the evidence necessary to support claims so victims understand how injuries translate into recoverable damages.
This mapping shows why early and ongoing medical evaluation, expert assessments, and life-care planning are crucial for accurately valuing and proving losses in serious injury cases.
How Is Whiplash and Soft Tissue Injury Compensated in Texas?
Soft tissue injuries like whiplash often produce significant pain and functional limitations, but because they are less visible on imaging, consistent medical treatment records and therapy documentation are essential to substantiate claims. Claimants should attend recommended physical therapy, follow medical advice, and keep detailed treatment and symptom logs to connect care to injury. Insurers scrutinize gaps in treatment or inconsistent reporting, so timely medical follow-up enhances credibility. Accurately recorded treatment progression supports both economic damages (bills) and non-economic damages (pain and suffering) in negotiations or at trial.
Clear medical continuity and objective clinical findings improve recovery prospects for non-visible injuries.
What Are the Legal Challenges of Traumatic Brain Injury Cases?
TBI cases involve diagnostic complexity and substantial long-term care needs, requiring neuropsychological testing, specialized medical opinions, and life-care plans to quantify future support and cognitive impairment. Proving causation and linking functional deficits to the crash often depends on expert testimony and baseline comparisons, and insurers may dispute the extent or permanence of cognitive injuries. Given these valuation complexities, attorneys coordinate with neurologists, neuropsychologists, and vocational experts to build a comprehensive claim for past and future losses. The high stakes of TBI cases make early preservation of medical and neurocognitive data essential.
Expert collaboration and rigorous documentation are central to obtaining full compensation for TBI-related harms.
How Do Spinal Cord Injuries Affect Wrongful Death and Catastrophic Accident Claims?
Spinal cord injuries that result in paralysis or death create catastrophic claims with lifetime medical costs, nursing care needs, and profound economic and non-economic losses; when a fatality occurs, wrongful death actions allow eligible family members to seek damages for loss of support and companionship. Valuing these claims requires life-care plans, medical cost projections, and expert testimony to establish long-term needs and lost earning capacity. Legal strategies must also address liability sources and secure timely preservation of evidence given the scale of economic consequences. Catastrophic injury and wrongful death claims thus demand specialized legal and medical expertise to fully quantify and pursue recovery.
Quantifying future care and losses is central to achieving fair compensation in catastrophic and fatal cases.
When Can Families File Wrongful Death Claims After a Fort Worth Car Accident?
Under Texas law, certain family members may file wrongful death claims when a crash causes a fatality, with statutes specifying who is eligible and what types of damages are recoverable, including loss of companionship and mental anguish for certain survivors. The wrongful death statute also imposes filing deadlines, typically within two years of the death, so families must act promptly to preserve legal rights. Evidence supporting wrongful death claims includes medical records, death certificates, accident reports, and expert opinions on causation and economic loss. Timely consultation with counsel helps families evaluate eligibility and file within statutory timeframes to pursue compensation.
Prompt legal assessment ensures families do not lose critical rights due to missed deadlines or incomplete evidence.
How Can You Navigate Insurance Claims and Negotiations After a Fort Worth Car Wreck?
Navigating insurance negotiations requires understanding what adjusters look for, avoiding common mistakes that reduce claim value, and recognizing when litigation is the appropriate next step to secure fair compensation. Adjusters evaluate liability evidence, medical causation, treatment continuity, and pre-existing conditions to assess exposure, while claimants can preserve value by maintaining records and avoiding admissions of fault. This section supplies do/don't guidance and a checklist for deciding whether to accept a settlement or proceed to litigation.
Insurance adjuster perspectives can be summarized in a short checklist to protect claim value.
- Adjusters prioritize clear liability proof and consistent medical causation linking treatment to the crash.
- Gaps in treatment or inconsistent symptom reporting are red flags that reduce offers.
- Pre-existing conditions lead adjusters to argue reduced causation; documentation is needed to isolate crash-related harm.
Keeping this checklist in mind helps victims identify weak points in a claim, and the next subsection describes those red-flag mistakes to avoid directly.
What Are Insurance Adjusters Looking for in Your Car Accident Claim?
Adjusters search for liability documentation, medical records showing causation, treatment gaps, and any facts that suggest pre-existing conditions contributed to injuries; these items shape settlement calculations. Early and consistent medical care, complete documentation, and witness statements increase credibility and negotiating leverage. Adjusters also review police reports and physical evidence to assess fault, and they may attempt to obtain recorded statements to use against claimants. Recognizing these priorities lets claimants focus on collecting the specific evidence that neutralizes adjuster defenses.
Understanding adjuster priorities guides how to present a claim and when to involve counsel to protect claim value.
How to Avoid Common Mistakes When Dealing With Insurance Companies
Do not admit fault, do not give recorded statements without legal counsel, and do not accept the first settlement offer without documenting future needs; these mistakes commonly reduce recovery. Instead, promptly document injuries, follow prescribed medical care, keep a communication log with insurers, and seek legal advice before signing releases. Save all bills, invoices, and correspondence, and request written explanations for any denials or low offers so counsel can evaluate next steps. Taking these precautions preserves negotiation leverage and positions a claim for fairer resolution.
Avoiding these mistakes increases the likelihood that offers will reflect the true value of medical, economic, and non-economic losses.
When Should You Consider Litigation Over Settlement Offers?
Consider litigation when settlement offers do not cover full current and projected losses, when liability disputes remain unresolved, or when an insurer engages in bad-faith tactics that impede fair recovery. Factors to weigh include the strength of liability and damages evidence, the difference between the offer and the claim’s full value, and the cost-benefit of pursuing trial given statute of limitations deadlines. Your attorney can model expected trial outcomes and advise whether a lawsuit strengthens negotiating leverage or is necessary to secure full compensation. Remember that filing suit preserves legal rights under the statute of limitations and may prompt more serious settlement consideration from insurers.
A reasoned decision checklist, informed by counsel, helps determine when litigation is the right strategic move.
Where Can Fort Worth Car Accident Victims Find Legal Resources and Support?
Victims should compile key documents, reach out to qualified local counsel for a free consultation, and use Fort Worth and Tarrant County resources for crash reports and medical care. Helpful contacts include the Fort Worth Police Department for crash reporting, TxDOT and regional traffic authorities for crash data, and local hospitals for emergency treatment and records. Howard Lotspeich Alexander & Williams, PLLC is one of the local options offering free consultations and contingency-fee representation, and victims should compare resources and seek a confidential review to preserve deadlines and plan next steps. This section outlines how to schedule consultations, which local resources to consult, and brief PAA-style answers to common questions.
Below is guidance on scheduling a free consultation and preparing to make that meeting productive.
- Contact a Fort Worth car accident lawyer to request a free consultation and bring the police report number, photos, medical records, and any correspondence with insurers.
- Expect an initial case evaluation covering liability, potential damages, and statutory deadlines; the attorney can advise whether immediate preservation steps are needed.
- Because many firms handle cases on contingency, you may be able to obtain representation without upfront attorney fees, allowing focus on recovery rather than legal costs.
Preparing documents and questions before a consultation helps maximize the benefit of the free review and positions your case for timely action.
How to Schedule a Free Consultation With a Fort Worth Car Accident Lawyer
To schedule a free consultation, identify local firms that offer no-cost initial evaluations and prepare key documents to streamline the review: the police report number, photos of the accident, medical records and bills, and any insurance communications. A productive consultation will assess liability evidence, explain damages categories, and outline potential timing for filing suit under Texas deadlines. When contacting a firm, ask about contingency-fee arrangements, how costs are handled, and what immediate preservation steps the firm recommends. A clear agenda and documents ready at the consultation optimize the attorney’s ability to evaluate claims and advise on next steps.
An informed, prepared consultation helps you and the attorney quickly determine the best path forward while protecting critical legal rights.
What Local Fort Worth and Tarrant County Resources Assist Accident Victims?
Fort Worth police facilitate crash reporting and access to official reports; regional agencies such as state transportation authorities collect crash statistics and offer data helpful for trends and investigations. Local hospitals and trauma centers provide emergency care and maintain the medical records essential for claim substantiation, while victim assistance programs and county resources can help survivors navigate immediate needs. When investigating commercial or truck crashes, regulatory records and federal carrier logs may also be relevant and are typically obtained by counsel or investigators. Combining law enforcement reports, medical records, and transportation data creates the documentation backbone of a strong claim.
Using these local resources in coordination with counsel ensures you obtain authoritative documentation required for insurance negotiations or litigation.
What Are Frequently Asked Questions About Fort Worth Car Accident Cases?
- How long do I have to file a car accident claim in Texas? — Generally two years from the date of injury to file a personal injury lawsuit, though certain narrow exceptions may apply.
- What is comparative fault in Texas car accidents? — Texas uses modified comparative fault with a 51% bar: if you are 51% or more at fault, you generally cannot recover damages; otherwise your recovery is reduced by your percentage of fault.
- Do I need a lawyer for a minor car accident? — While minor claims can sometimes be handled without counsel, consulting an attorney helps evaluate whether full damages, including future care, are being considered before settlement.
- Who pays medical bills after a car accident in Fort Worth? — Initially, emergency providers, insurers, or personal health insurance may cover bills, but responsible-party liability and subsequent settlements determine ultimate payment and reimbursement.
- Can families file wrongful death claims after a Fort Worth car crash? — Eligible family members may file wrongful death actions under Texas law, subject to statutory requirements and filing deadlines; early legal evaluation is important.
These short answers are designed for quick reference; discussing details with counsel will clarify how rules apply to your specific facts and help protect claim value.
 Under the typical Texas liability insurance policy both the insurer and the insured have mutual obligations and rights. The insured pays a premium to their insurance company to protect against unexpected losses and claims. On the other hand, the insurance company has a duty to defend against claims covered under the policy and a right to control the defense of litigation should it arise.
 Many people involved in motor vehicle collisions may not have police or accident reports documenting the specifics of the wreck. Sometimes it could be because the wreck was not reported and the police were never called. Other times, the police may have been called but simply did not respond. Law enforcement agencies often lack the resources to respond to each and every car wreck that occurs in their jurisdiction. More and more police agencies are putting policies into place that do not require them to respond to what the agency deems a “minor” wreck. The problem is that sometimes a wreck that law enforcement deems “minor” may actually have major long-term consequences (and injuries) for the individuals involved.